Mon–Fri 8am–6pm · Sat 8am–3:30pm PT
Fix and flip loans for the purchase and the rehab.
Purchase, renovate, and sell investment properties with financing built for house flips. LGV Capital qualifies on the project — not your personal income — and funds both the acquisition and renovation, so you keep cash free for the next deal.
- Up to 93% LTC + 100% of the rehab budget. Funded in draws as the work completes.
- Loans from $150K to $8M. SFR through small multifamily, 6–30 month terms.
- Asset-based qualification. No tax returns or W-2s required for qualification — underwriting focuses on the property and the project.
- First-time flippers welcome. Pair with a licensed contractor and a solid scope.
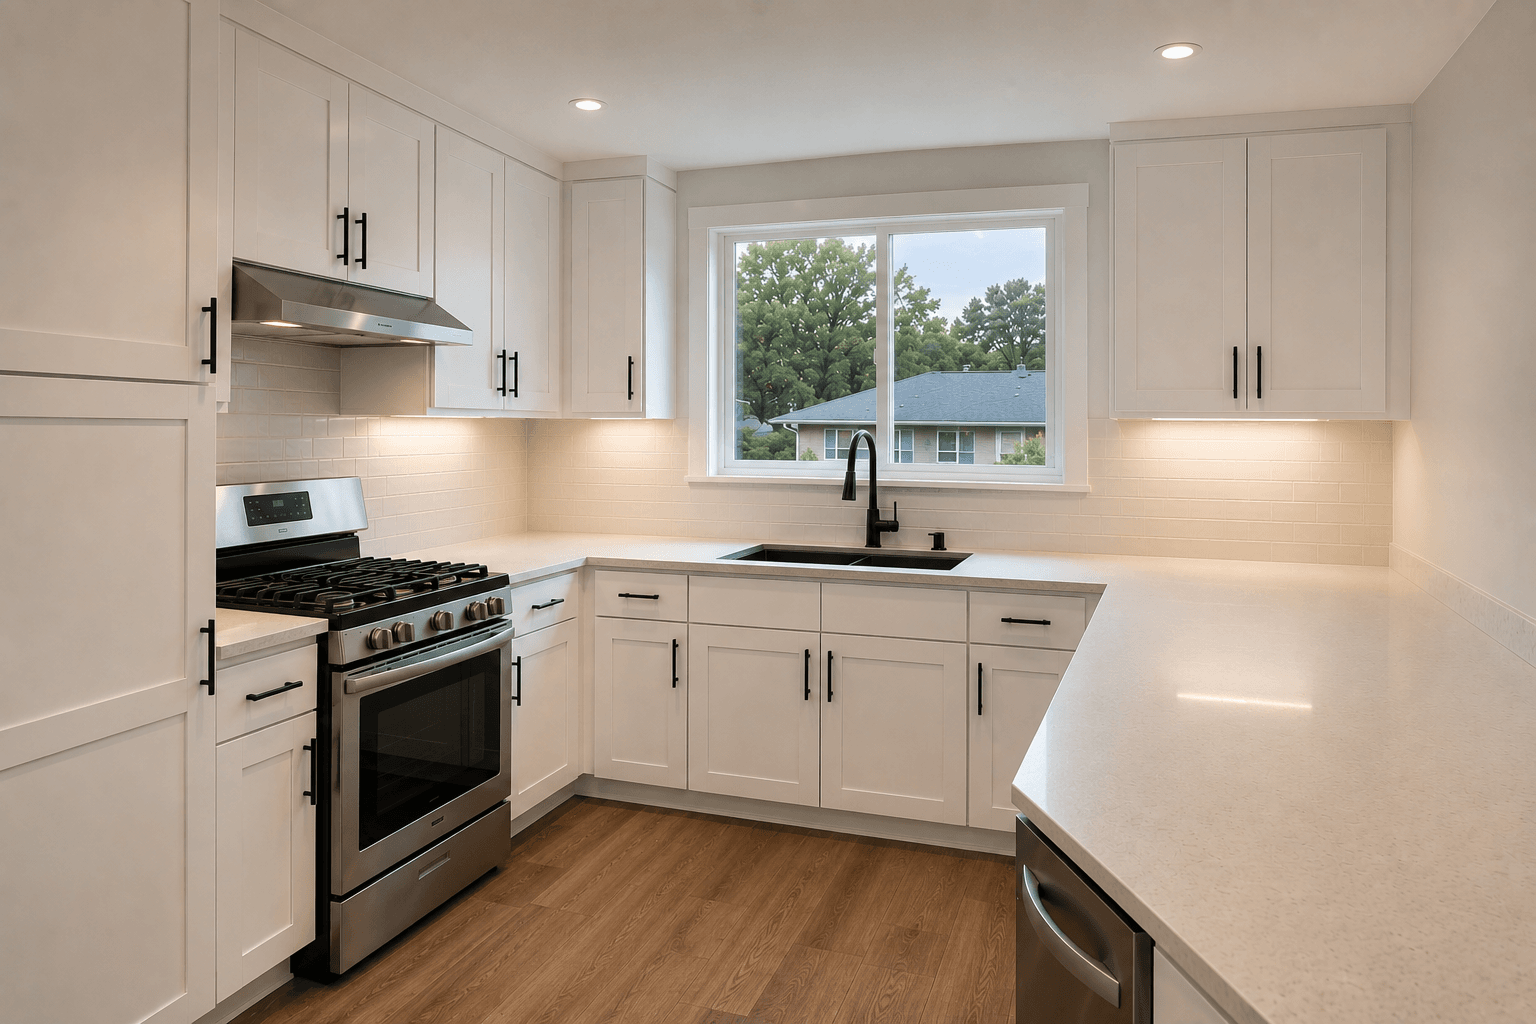
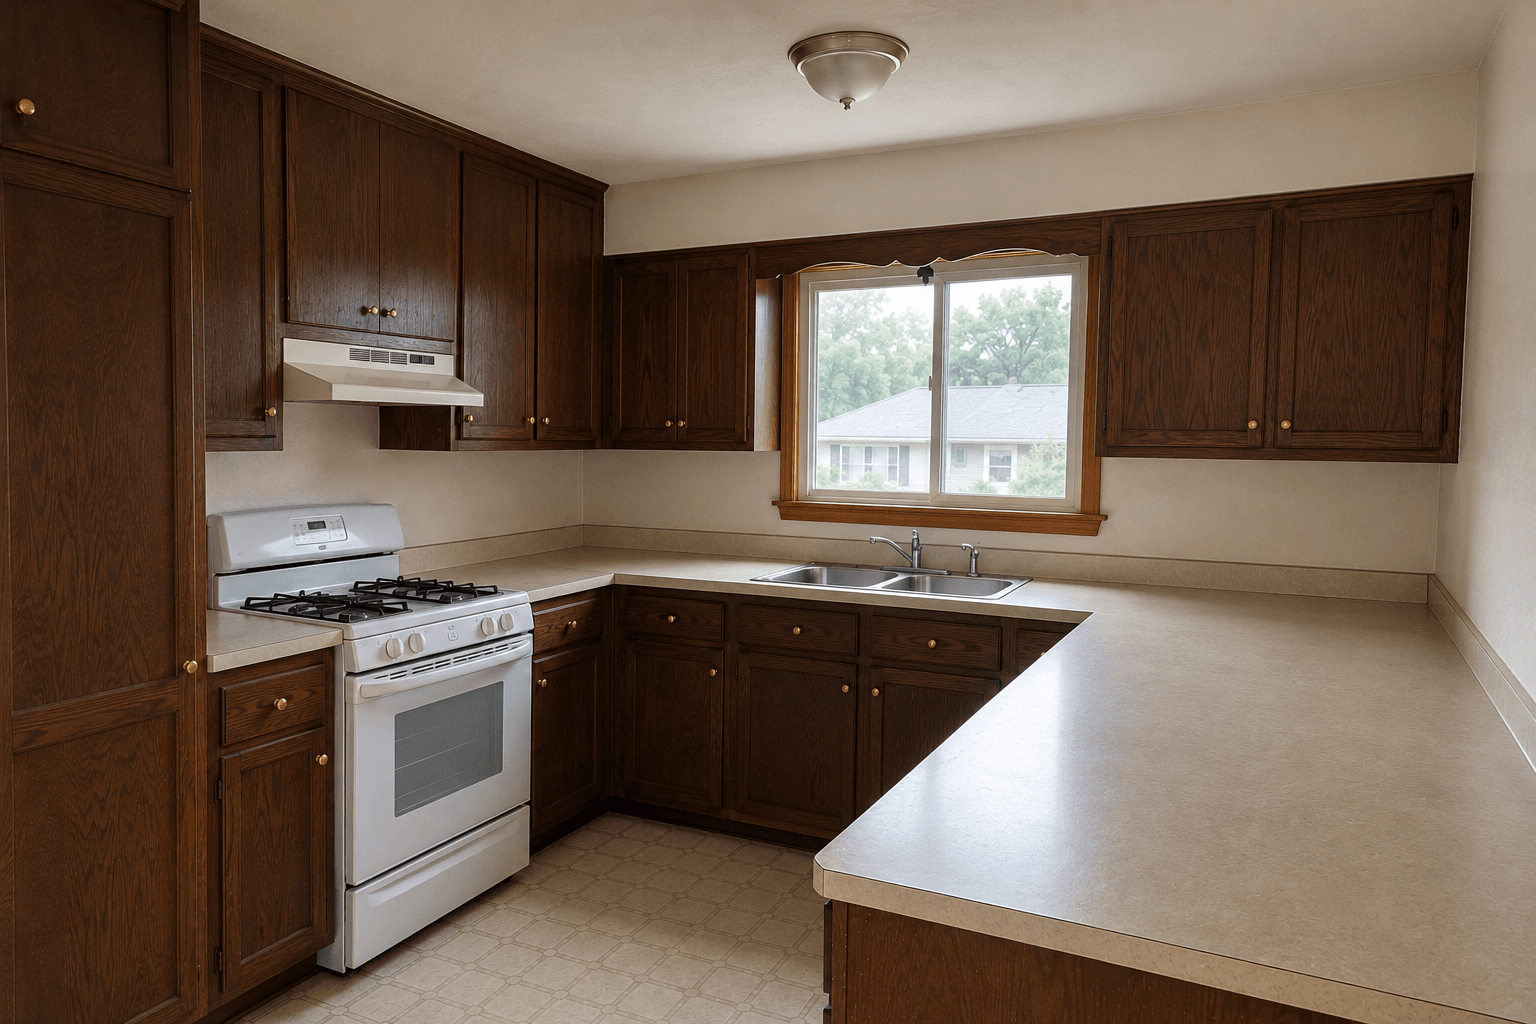 Before
After
Run your flip — see if it pencils
Plug in your numbers below. The calculator shows your estimated gross spread, cash required, and how much LGV Capital could finance based on your experience level.
Your Deal
Estimates only. Cash to close covers your share of the purchase; rehab is funded in draws that reimburse completed work. Maximum LTC depends on experience, credit, and project economics. Final terms vary by deal. Not a loan offer or pre-approval.
Like what you see? Request a term sheet to lock in your actual numbers — no application fee, no obligation to proceed.
Fix & Flip Loan Requirements & Eligibility
These are the standard qualification guidelines used to evaluate LGV Capital fix and flip loans. Final terms vary based on the property, scope, experience, and exit strategy.
Credit is reviewed but income documentation is not required.
Flexible financing for single-property flips through small portfolios.
Tier-based; first-time flippers typically qualify for 80–85% LTC.
Interest-only payments structured around your project timeline.
Non-owner-occupied SFR, condos, townhomes, 2–4 plex, and up to 11-unit properties.
Pair with a licensed general contractor and a clear scope of work.
Find the flip that matches your strategy
A fix and flip loan from LGV Capital covers the most common flip scenarios investors run. Choose the one that matches your deal to see how it works.
Choose your scenario
Cosmetic & light rehab flips
Single-family or 2–4 plex flips with mostly cosmetic work — kitchen and bath updates, paint, flooring, fixtures. The fastest path to a flip and the most common deal type LGV Capital finances.
Heavy rehab & value-add
Down-to-the-studs renovations — full kitchen rebuilds, structural work, additions, layout changes. Higher rehab budgets, longer timelines, bigger margins. Funded in draws as the work progresses.
Auction & distressed acquisitions
Foreclosures, REOs, auction purchases, and off-market distressed deals — the kind that need fast, certain financing. Asset-based qualification lets LGV Capital move on deals that don’t fit a traditional lending box.
2–4 plex & small multifamily flips
Multi-unit value-add deals — unit turns, common-area renovations, rent repositioning. Sell as a stabilized cash-flowing asset, or exit into a long-term DSCR loan and hold for the long run.
Five reasons flippers pick LGV Capital
LGV Capital structures every fix and flip around the property, the project, and your experience — not your W-2.
Top-tier leverage
Up to 93% LTC on purchase plus 100% of the rehab budget — financed in draws as the work completes. Most fix and flip lenders cap leverage at 75–80%.
Close in 10–14 days
From submission to funding in under two weeks. Win auctions, beat conventional buyers, and move on time-sensitive deals the way active flippers actually need.
First flips welcome
Pair with a licensed general contractor and a clear scope, and first-time flippers qualify for up to 85% LTC. Real funding for real beginners, not just experienced operators.
One partner, end-to-end
Sell the flip or pivot to a long-term DSCR loan if you keep it as a rental. Same team, no re-qualifying, no broker hand-offs.
Asset-based qualification
No tax returns, no W-2s, no DTI calculations. The property and project carry the deal, not your personal income.
LGV Capital vs. typical fix & flip lenders
Same deal, two ways to finance it. One keeps more of your capital working.
| Factor | LGV Capital Fix & Flip Investor pick Underwritten on the project, built for the flip | Typical Lender Lower leverage, slower, more paperwork |
|---|---|---|
| Max LTC (purchase) | Up to 93% | 75–80% |
| Rehab financing | 100% of budget | Often partial |
| Time to close | 10–14 days | 3–6 weeks |
| Payment structure | Interest-only | Often P&I |
| Income verification | Not required | Often required |
| First-time flippers | Welcome with GC | Often declined |
| Entity / LLC vesting | Fully supported | Limited |
| Exit to long-term DSCR | Same partner | Refer out |
| Get a term sheet |
One partner. Every stage of the flip.
Get a term sheet today. Close in 10–14 days. Keep more capital in play across more deals.
Funded in 10–14 days, released in coordinated draws.
LGV Capital covers up to 93% LTC on purchase and 100% of rehab on flips from $150K to $8M — same-day term sheets, parallel processing, and draws tied to completed work.
100% financed, released as work is completed
- Kitchen & baths40%
- Flooring & finishes25%
- Mechanicals20%
- Exterior & misc15%
Four steps, typically 10–14 days
-
1Profile & terms Day 1
Property, rehab budget, ARV target — we size the deal and issue a written term sheet the same day.
-
2Processing Days 2–8
Title, ARV appraisal, scope of work, contractor verification, and entity docs run in parallel.
-
3Underwriting Days 8–12
Deal economics validated. Purchase plus rehab versus ARV — we want to see a real project margin.
-
4Funded Days 10–14
Purchase funds wire at closing. The rehab budget is held back and released in draws as work is completed and inspected.
We size deals around the project, not just the paperwork. Timelines vary with appraisal and title.
Get a term sheetFlippers who closed faster, financed more, and kept their cash.
"First flip and I figured nobody would lend to me. LGV walked me through everything and got the deal closed. Couldn't have asked for a better first experience."
Funded: $295K Fix & Flip · First Flip · Tampa, FL"Bought at $510K, put $180K into the rehab, sold at $890K six months later. Walked away with around $145K after costs. LGV made it possible to do this with less of my own cash."
Funded: $654K Fix & Flip · Experienced · Atlanta, GA"Other lenders passed on a foreclosure I wanted. LGV closed it in 11 days. Easiest part of the whole project."
Funded: $410K Fix & Flip · Distressed · Phoenix, AZCommon Fix & Flip Loan Questions, Answered
A fix and flip loan is short-term, asset-based financing — typically 6 to 30 months — that covers both the purchase and the rehab budget for investors buying, renovating, and reselling investment properties. LGV Capital qualifies fix and flip loans on the property and project economics, not personal income, so deals typically close in 10 to 14 days.
LGV Capital finances up to 93% of the purchase price (LTC) plus 100% of the rehab budget. Maximum leverage is tier-based: first-time flippers typically qualify for up to 85% LTC, intermediate flippers up to 90% LTC, and experienced flippers up to 93% LTC. The 100% rehab financing applies across all tiers. Final leverage depends on the property, project, and borrower profile.
Most LGV Capital fix and flip loans fund in 10 to 14 days from initial submission. Speed depends on appraisal turn time, title work, and the cleanliness of the deal. Asset-based qualification keeps underwriting focused on the property and the project, which keeps the process moving.
Yes. LGV Capital welcomes first-time flippers when paired with a licensed general contractor and a clear scope of work. First-time flippers typically qualify for up to 85% LTC with 100% of the rehab budget financed. The contractor relationship strengthens the deal because it gives the project a credible execution plan.
The rehab budget is financed in draws — reimbursements released as work is completed and inspected. You front each phase of work, request a draw, and LGV Capital releases the funds once the inspector confirms completion. Draws typically fund within a few business days of inspection. This structure keeps your loan balance growing with project progress, not all at once.
Minimum FICO is 650. Stronger credit profiles get better rates and higher leverage tiers, but credit is one factor among the property, the project, and your experience.
LGV Capital fix and flip loans cover non-owner-occupied investment properties: single-family homes, condos, townhomes, 2–4 unit properties, and multifamily up to 11 units. Loan amounts range from $150K to $8M.
No. LGV Capital fix and flip loans are asset-based. You do not need W-2s, tax returns, or DTI calculations to qualify. Approval is based on the property, the project economics, and your experience level.
Fix and flip loan rates vary based on loan-to-cost, credit score, property type, experience level, and term length. Rates are typically higher than long-term financing because of the speed and flexibility. The most accurate pricing comes from a term sheet on your specific deal.
Yes. LGV Capital fix and flip loans use interest-only payments through the hold period, which keeps monthly carrying costs lower while you renovate and prepare the property for sale.
Yes. Fix and flip loans are commonly issued to LLCs and other business entities, which is standard practice for active investors holding properties in entities for liability and tax purposes.
Most LGV Capital fix and flip loans have no prepayment penalty after a short minimum interest period, so you can exit when the property sells without paying a penalty. This is critical for flippers — your business model depends on selling the property and paying off the loan as fast as possible.
Fix and flip projects often run longer than initial estimates. LGV Capital terms run 6 to 30 months specifically to give projects realistic timeline cushion. If the project runs past the initial term, extensions and restructures are available — communicate with us early and we work with you on the path forward.
Yes. If you decide to keep a flip as a rental instead of selling it, you can refinance into a long-term DSCR loan with LGV Capital once the property is renovated and rentable. Same partner, no re-qualifying with a new lender.
Yes. Auction purchases require fast, certain funding — exactly what fix and flip financing from LGV Capital is built for. We can pre-approve you ahead of an auction so you can bid with proof of funds and close within tight auction payment windows.
After-repair value (ARV) is determined by a licensed appraisal that values the property based on the planned scope of work and recent comparable sales. The appraisal is ordered during the loan process and is part of the standard underwriting workflow.
Yes. LGV Capital lends to foreign national investors on U.S. fix and flip projects. Foreign national loans typically require larger down payments and additional documentation. Credit and documentation requirements differ from domestic borrowers, so talk with our team about your specific situation.
Fix and flip closing costs typically include origination points, appraisal, title insurance, and standard closing fees. Exact costs vary by loan size, property location, and deal complexity. All fees are disclosed upfront in your term sheet — no surprises at closing.
Still have questions?